What the appeals court decision means
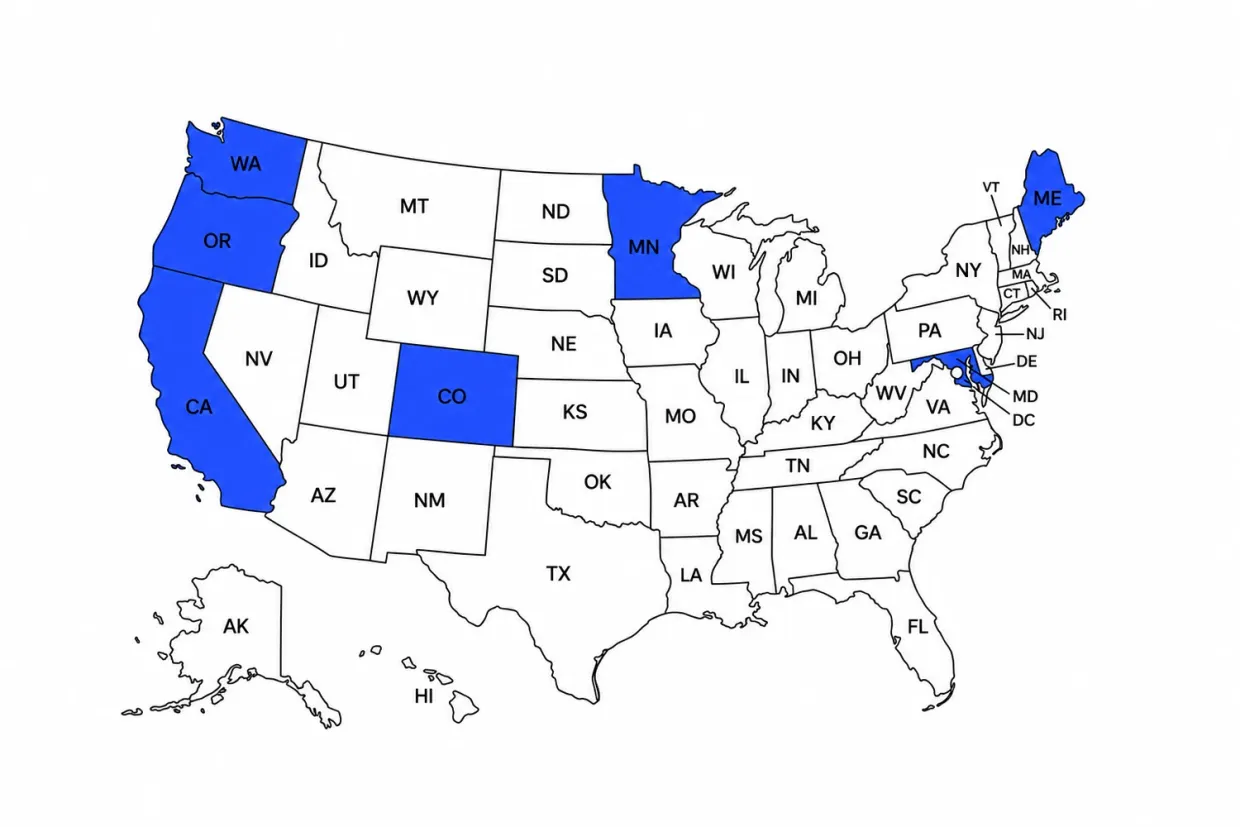
The ruling concerns California’s Corporate Data Accountability Act, known as SB 253, and the related Climate-Related Financial Risk Act, SB 261. The legal challenge raises questions about California’s authority to require corporate climate reporting and about how CARB can implement the laws through its administrative law and rulemaking process.
The appeals court has blocked or paused key parts of the laws rather than resolving every issue on the merits. The final impact will depend on the scope of the order, subsequent court actions, and CARB’s enforcement position.
Companies should avoid two opposite mistakes: assuming every requirement is immediately enforceable, or assuming all preparation can stop. SB 253 has already made emissions data, reporting frameworks, assurance readiness, and climate risk management priorities for finance, procurement, legal, and operations teams.
What does SB 253 require?
SB 253 requires covered companies to report greenhouse gas emissions in accordance with the Greenhouse Gas Protocol. The requirements cover:
- Direct emissions: Emissions from owned or controlled operations.
- Purchased-energy emissions: Indirect emissions from purchased electricity.
- Value-chain emissions: Emissions connected to suppliers, customers, logistics, business travel, and other activities.
Companies must also obtain third-party verification of reported emissions data. Scope 3 is the most difficult requirement because the data sits outside a company’s direct control. Supplier engagement, consistent calculation methods, reasonable estimates, and audit trails will all matter. Smaller suppliers may receive more emissions-data requests from larger customers.
CARB has provided an important first-cycle enforcement clarification. It will not enforce penalties for incomplete first reports when a company makes a good-faith effort to file. Scope 3 penalties apply only for failure to file, not for every gap in the underlying data. Non-filing can still result in administrative penalties of up to $500,000 per year.
How does SB 261 fit in?
SB 261 applies to entities with more than $500 million in annual revenue. It requires a climate-related financial risk report every two years, covering potential effects on operations, assets, supply chains, capital planning, and risk management.
Penalties may reach $50,000 per entity per year, but enforcement is currently paused because of litigation. Companies should continue monitoring the public docket and CARB notices.
What should companies do next?
Companies can build a reporting foundation that adapts as the rules change. Key steps include:
- Confirm the relevant revenue threshold and California business activities.
- Assign ownership across finance, procurement, legal, operations, and internal audit.
- Map the emissions boundary and document calculation methods.
- Prioritize high-impact suppliers and create a data-request process.
- Record assumptions, estimates, and data-quality improvements.
- Prepare controls that can support third-party assurance.
A reasonable first report does not require perfect data on day one. It does require a defensible methodology, a clear record of assumptions, and a plan to improve data quality over time.
For more detail, see Sweep’s SB 253 expert guide featuring former CARB Chair Liane Randolph. Deel’s customer story shows how a global company built a report-ready emissions foundation across 150 countries.
The court decision may change timing, enforcement, or specific reporting obligations. It does not change the value of reliable emissions data. Companies that prepare now can reduce reporting friction, improve risk management, and respond faster as California’s legal and regulatory picture becomes clearer.